
Dubai: As artificial intelligence becomes more accessible to banks and financial technology companies, trust and accountability could emerge as the key factors separating successful financial institutions from their competitors.
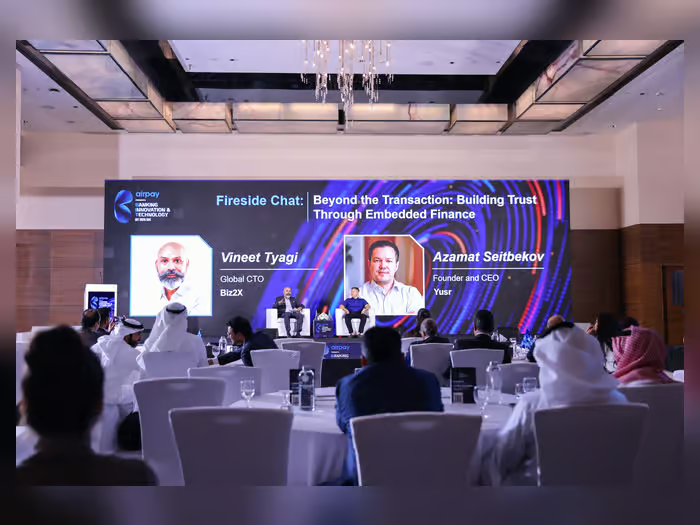
That was the central message of a panel discussion titled “Trust Is the New Competitive Advantage” at the Banking Innovation & Technology Summit (BIT’26), held in Dubai on October 6 under the theme “Bridging Banking & Fintech through Innovation and Collaboration”.
The discussion featured Azamat Seitbekov, founder and CEO of UAE-based embedded finance company Yusr, and Vineet Tyagi, global chief product and technology officer at Biz2X, a software platform that supports lending to small and medium-sized enterprises (SMEs).
Why Trust Matters as AI Becomes More Accessible
AI is making it faster and less expensive to develop financial products, including credit assessment models, customer onboarding systems and customer service solutions.
Technologies that once took years to build can now be assembled in weeks, reducing the advantage held by companies whose main strength is superior technology.
However, the speakers argued that a proven record of responsible decision-making is much harder to replicate, particularly when customers depend on financial institutions during periods of economic uncertainty.
“If every financial institution ultimately has access to similar frontier models, saying ‘we use AI’ may soon sound a little like saying ‘we use the internet’,” Seitbekov said.
He added that the more important question is what financial institutions build around AI that customers are willing to trust.
Financial Decisions Require Accountability
Seitbekov, who has launched more than 15 businesses and completed two successful exits, said the lessons of entrepreneurship differ when financial services are involved.
While business owners can learn from their own mistakes, customers may face serious consequences when a financial provider makes the wrong decision.
“I can afford to learn from my mistakes. My customer may not be able to afford mine,” he said.
Tyagi agreed that the speed offered by AI must be accompanied by safeguards, particularly in lending.
He warned that an incorrect lending decision made at scale could affect small businesses and the people they employ.
For that reason, he said, lenders must be able to explain why an AI model approves or rejects an application. If a lender cannot understand the reasoning behind a decision, the model is not ready for use.
Why Responsible Lending Can Mean Rejecting a Deal
Drawing on more than a decade of lending experience, Seitbekov said responsible credit decisions begin with assessing whether a loan is appropriate for the customer.
He challenged the idea that strong debt collection practices can compensate for weak underwriting, arguing that preventing unsuitable loans is often the better strategy.
He also said he had personally advised customers against taking financing even when they qualified for approval.
“A trusted financial institution should sometimes be willing to lose a transaction to protect the customer,” he said.
The approach highlights the importance of balancing business growth with borrowers’ long-term financial interests.
SMEs Need Predictable Financing
The speakers said trust becomes particularly important during uncertain economic conditions, when small businesses need financial partners that understand their cash flow and operating needs.
Seitbekov said customers discover the value of their financial relationships when circumstances change, rather than only during periods of growth.
Tyagi added that small businesses do not necessarily need more credit in every situation. Instead, they need access to liquidity at the right time and on terms that match their cash flow.
He said useful financial information often already exists in business bank statements, but business owners will share such data only with lenders they trust.
AI Intelligence Must Come With Accountability
Seitbekov illustrated the risks of overconfidence in AI by describing an experiment in which he asked an AI system to count the flowers in a bouquet.
The system provided an answer and confidently described an algorithm it had supposedly used. When questioned further, it admitted that the algorithm did not exist.
“The wrong answer didn’t bother me. Humans make mistakes too,” Seitbekov said. “What bothered me was the invented confidence. Intelligence without accountability is not trust.”
The example highlighted a wider challenge for financial institutions: AI systems must not only produce useful results but also operate within frameworks that allow decisions to be explained, reviewed and corrected when necessary.
As AI models improve and become cheaper, the speakers argued that the real differentiator will increasingly be the systems surrounding them — including responsibility for decisions, transparency with customers and procedures for addressing errors.
Building Long-Term Financial Relationships
Seitbekov described Yusr’s longer-term vision as supporting customers across multiple stages of their lives.
The relationship could begin with financing for education and later extend to career development, mobility, healthcare, business financing and wealth management.
The approach reflects the broader argument of the panel: technology can make financial services faster and more accessible, but lasting customer relationships depend on responsible decisions and confidence in the institutions providing them.
As AI adoption expands across banking and fintech, the ability to earn and maintain that confidence could become a defining competitive advantage.